
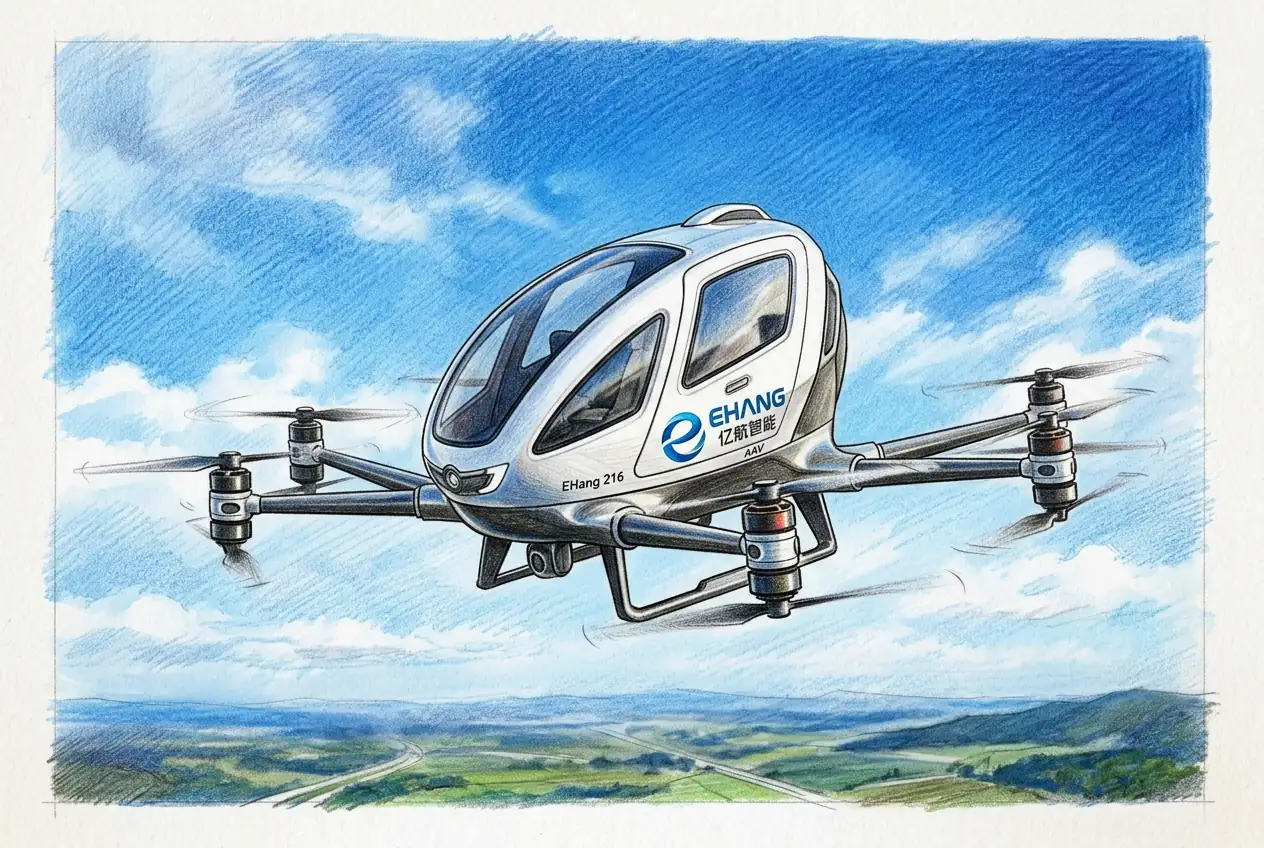
Shares shifted as EHang Holdings surged 7.1% to $5.57 in pre-market trading ahead of its second-quarter 2026 earnings release, due before the opening bell today with an 8:00 a.m. ET conference call to follow. The bet is clear: traders believe Q2 numbers will show a sharp recovery from a brutally weak first quarter — and the stakes are high for a company trying to prove that pilotless flying taxis are a real business, not just a demo reel.
Q1 Was a Near-Standstill, So Even Modest Improvement Looks Big. EHang delivered just four aircraft in Q1 2026, down from 11 a year earlier and 66 the prior quarter.
Revenue cratered to RMB 25.7 million ($3.7 million), versus RMB 177.6 million in Q4 2025. That quarterly collapse was so severe that virtually any uptick in Q2 deliveries would produce a headline-grabbing percentage improvement — which may be exactly what pre-market buyers are banking on.
Management Needs the Back Half to Deliver on a RMB 600 Million Promise. EHang maintained full-year 2026 revenue guidance of around RMB 600 million — roughly +18% year-over-year. With only RMB 25.7 million booked in Q1, roughly RMB 574 million must land across the final three quarters. Management said it expects most 2026 orders to arrive in the second half, noting that many customers are government-related entities whose budget approvals are typically completed later in the year. Today's report is the first real test of that claim.
Wall Street Has Already Grown More Cautious. UBS cut its rating from Buy to Neutral and slashed its shipment and revenue forecasts for 2026–2028 by 50% to 70%.
Goldman Sachs downgraded EHang to Neutral in July, and Morgan Stanley cut its price target to $7.70 from $26.
The median analyst target now sits at just $5.40 — barely above today's price — signaling limited upside unless results surprise significantly.
The Real Catalyst Is Commercial Ticket Sales, Not Aircraft Shipments. EHang's two certified operators completed a year of trial flights in Guangzhou and Hefei and were expected to begin public ticketed sightseeing service in March 2026.
In Thailand, management has targeted up to 100 aircraft across 20 sites by year-end. Any concrete Q2 update on paying passengers or overseas revenue — which management projected could reach 10% of total revenue — would matter far more than unit counts alone.
With RMB 1.03 billion in cash on hand and a $30 million buyback authorized, EHang isn't facing a liquidity crisis. The crisis is one of credibility: proving the transition from test flights to ticket counters is actually happening.