
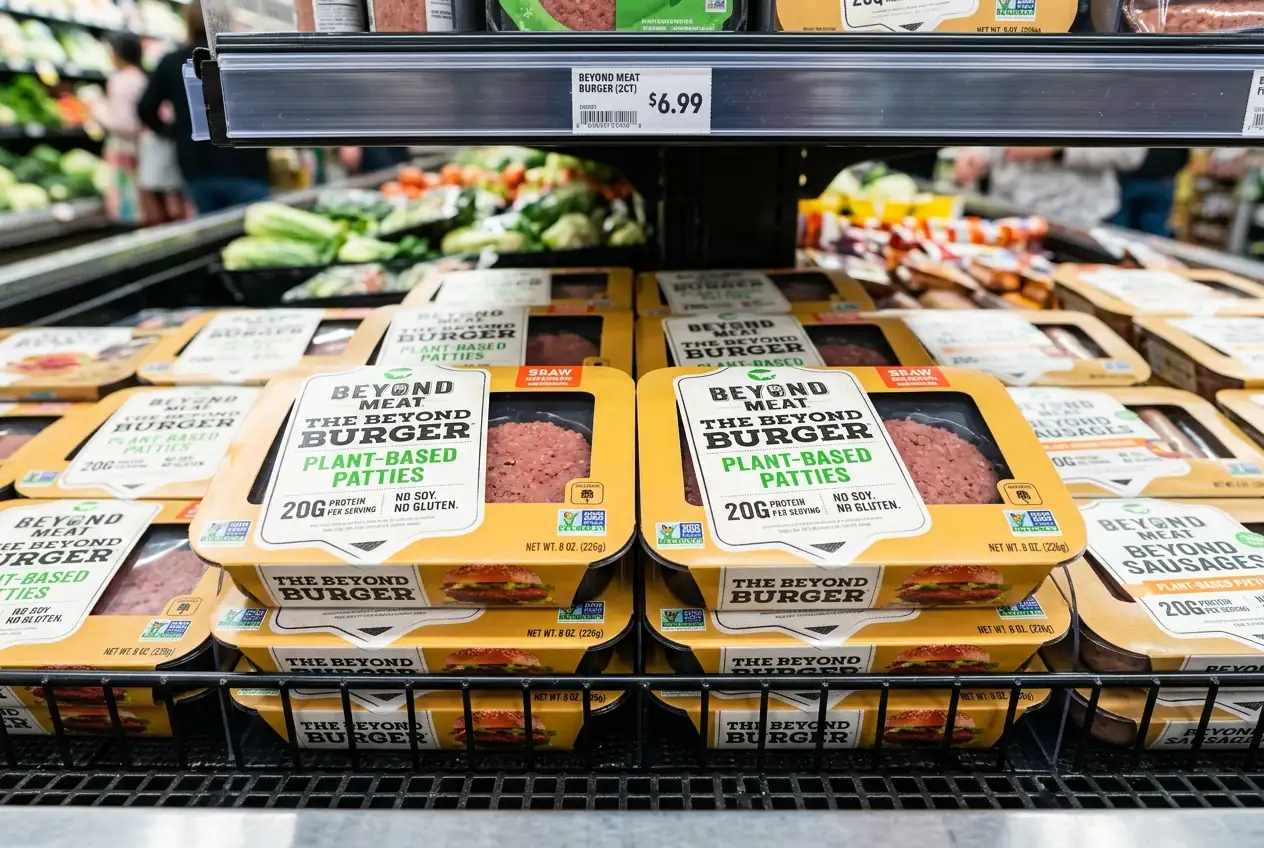
Shares of Beyond Meat tumbled 7.5% to $10.65 on September 23 after the plant-based protein company announced it would swap roughly $15 million in convertible debt for common stock — a move that chips away at its debt pile but hands existing shareholders a smaller slice of the company. Beyond Meat Trades Debt for Dilution Again — Is There Any Equity Left Worth Owning?
Shares of Beyond Meat sank 7.5% to $10.65 after the company disclosed yet another privately negotiated swap of debt for stock, underscoring a painful reality: the plant-based protein maker keeps shrinking its debt by shrinking what each share is worth.
• Another Round of Dilution Hits a Stock Already Battered by Share Bloat
The latest deal converts roughly $15 million in zero-interest convertible notes into common shares, with an initial settlement of 1,097,444 shares and up to 848,265 more based on a three-day volume-weighted average price, floored at $7.40 per share. That floor means if the stock keeps falling, Beyond Meat will owe even more shares. This is not an isolated event. The company has increased its outstanding share count by 678% since its IPO , and as of August 2026 shares outstanding stood at roughly 515.3 million — turning what was once a premium growth name into a perpetual dilution machine.
• The Debt Mountain Is Smaller but Still Dwarfs the Entire Company
After last year's major restructuring, outstanding debt fell to about $411 million against $205 million in cash.
Yet the market cap now sits at just $190 million — meaning the debt alone is more than double the company's equity value. The restructured notes carry a 7% interest rate that now costs real money, unlike the old zero-coupon bonds. Every dollar of interest competes with an already-thin cash cushion.
• A $15.4 Million Trademark Bill Adds Insult to Injury
On September 18, the court ruled on post-trial motions in a trademark case, slashing actual damages from $23.5 million to just $37,500 but leaving a $15.4 million profit disgorgement intact.
For context, that sum equals roughly 22% of Q2 2026 revenue of $68.8 million. Appeals are possible, but the judgment hangs over a company that cannot afford surprises.
• Shrinking Sales Remove the One Escape Route
Net revenues declined 15% in the most recent reported quarter, and net losses narrowed only to $28 million.
Gross margins slipped to 5.61% in Q2 2026, while operating margin remains deeply negative at -117%. Without a revenue turnaround, Beyond Meat is left funding its survival by issuing stock — a vicious cycle where each share-for-debt swap signals distress, drives the price lower, and makes the next swap even more dilutive.